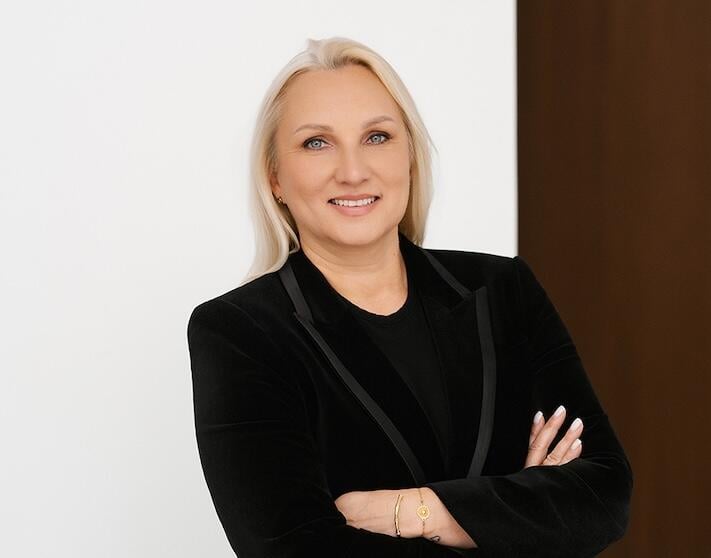
Laura Roke, commercial director at Magnetic Group.
Laura Roke, commercial director at Magnetic Group, speaks with Aviation Week about her perspectives on some of the aftermarket's biggest predictions — and which did not pan out the way industry analysts expected.
How has the longer-than-expected lifespan of CFM International CFM56 engines affected the aftermarket and Magnetic's engine strategy?
The CFM56 is a good example of how quickly market expectations can change in aviation. A few years ago, the general assumption was that as Leap-powered aircraft entered fleets, CFM56 demand would gradually decline. What we've actually seen is a much longer transition period.
There are several reasons for that. Aircraft delivery delays, supply chain constraints and challenges with new-generation engine availability have encouraged airlines to keep their existing aircraft flying longer. At the same time, the CFM56 has a proven track record, an established maintenance ecosystem and a large global installed base.
From an aftermarket perspective, this has created opportunities, but also challenges. Demand for serviceable engines, spare parts and maintenance capacity has remained strong, while the availability of suitable material has become increasingly important. GE Aerospace stated in September that CFM56 retirements were expected to remain around 1.5–2% for the year, supporting approximately 2,400 shop visits annually in both 2026 and 2027.
For Magnetic, the key lesson is that we need to follow the actual needs of the market rather than rely on predicted replacement timelines. That means maintaining a strong focus on mature engine platforms, understanding where the best opportunities exist across the engine lifecycle and being selective about investments in assets and material. I don't see the CFM56 disappearing from the aftermarket anytime soon, or as quickly as experts initially predicted. The market will eventually mature and contract, but the transition is likely to be much more gradual than originally anticipated.
We've seen similar dynamics with aircraft. How has the extended lifespan of legacy aircraft affected Magnetic's business?
The industry expected a relatively straightforward transition toward newer, more fuel-efficient aircraft, but the reality has been more complicated. The International Air Transport Association (IATA) reported in June that the global aircraft order backlog exceeded 18,000 and the average fleet age had reached 15.2 years, making it the oldest fleet in aviation history.
Airlines still want new-generation aircraft because of their fuel efficiency and environmental performance. However, aircraft production constraints, delivery delays and engine-related issues mean that many operators simply cannot replace their existing fleets as quickly as they planned.
As a result of the backlog, mature aircraft such as the Airbus A320ceo and Boeing 737NG remain highly relevant. Operators are investing in maintenance, cabin improvements and life-extension activities because keeping an existing aircraft in service is often the most practical option.
For Magnetic, this creates opportunities across several parts of the business, including aircraft maintenance, painting, CFM56 engine support, aircraft and engine component support, asset management and trading.
What is particularly interesting is that the aftermarket is no longer simply divided into old and new aircraft. Both generations need support, but in different ways. Mature aircraft require increasingly sophisticated lifecycle and material management, while newer platforms bring different technical requirements and maintenance challenges.
Our approach is to remain flexible and support both sides of that transition. In aviation, an aircraft's age alone doesn't determine its value. Its technical condition, operating economics and the availability of replacement capacity are equally important.
In recent years, we've started to see maintenance, repair and overhaul (MRO) providers dip their toes into opportunities to support the advanced air mobility (AAM) segment, including electric aircraft and electric vertical-takeoff-and-landing (eVTOL) aircraft.
How soon do you realistically think MRO will be impacted by electric aviation?
I believe electric aviation will have an impact on MRO, but it will happen in stages rather than through a sudden transformation. Developing an aircraft is one thing; certifying it, building the necessary infrastructure and operating it commercially at scale is something else entirely.
My expectation is that we'll first see meaningful maintenance demand from electric aircraft in smaller segments, such as pilot training, regional operations and AAM. For traditional commercial aviation MROs, the impact will take much longer — perhaps longer than we would like.
Electric propulsion also doesn't mean maintenance disappears. The requirements will change. Instead of focusing on conventional engines, MRO providers will increasingly need expertise in high-voltage systems, batteries, electric motors, thermal management and advanced diagnostics.
I think the next five years will be primarily about learning, developing technical capabilities and understanding the economics of maintaining these aircraft. Broader commercial opportunities are more likely to emerge in the 2030s, depending on certification progress and fleet growth.
A few years ago, we had very high hopes for 3D printing. Everybody expected it to reshape the aviation spare parts market, but it hasn't happened to the extent anticipated. Certification requirements, strict procedures and approval processes have slowed down the development and adoption of this technology.
For Magnetic, I would see electric aviation as an area to monitor closely and prepare for, rather than one that requires a major immediate shift in resources. We need to be ready for new technologies, but we also have to be realistic about where customer demand exists today.
Other technologies that have seen quite a bit of hype in recent years have been robotics and artificial intelligence (AI). I regularly hear from industry leaders that they expect these technologies to help MROs keep up with growing demand amid the ongoing labor shortage.
How do you think this dynamic is realistically going to evolve?
I think AI and robotics will absolutely change the MRO industry, but I don't believe they will replace skilled technicians. Aircraft maintenance is a highly regulated, safety-critical business. A lot of the work requires experience, physical judgment and the ability to deal with unexpected technical issues. You cannot simply automate all of that.
Where I see the greatest near-term potential is in reducing the amount of time our people spend on repetitive and administrative tasks — think about maintenance planning, technical documentation, inventory management, troubleshooting support and predicting which parts will be needed before an aircraft enters the hangar.
Robotics can also bring value in specific applications, such as inspections, repetitive measurements and certain cleaning or surface-treatment processes. But these solutions need to be practical and commercially justified.
The labor shortage isn't only about the number of technicians available. It's also about how effectively we use their time. If an experienced engineer spends hours searching for information or waiting for parts, that's time that could be spent working on an aircraft. I already see companies using AI for maintenance records reviews, and that's a great opportunity for further development.
For Magnetic, I believe the opportunity is to combine technology with the expertise of our people. The companies that benefit most from AI won't necessarily be those investing in the most sophisticated systems. They'll be the ones that successfully integrate technology into everyday operations.
Ultimately, AI should help our technicians do their jobs better, faster and with greater consistency, while keeping safety and human accountability at the center.
What's one prediction you have for how the aftermarket will evolve in the next decade?
My prediction is that the aftermarket will become much more focused on maximizing the value of existing assets throughout their entire lifecycle, with increasingly complex and integrated services. For a long time, the industry was built around relatively predictable aircraft replacement cycles. But recent years have shown that those cycles can change dramatically. Aircraft and engines are remaining in service longer, spare parts are becoming more strategically important and operators are looking for greater flexibility.
I expect the distinction between maintenance, asset management, leasing and spare parts trading to become less pronounced. Customers won't simply want an engine repair or an aircraft maintenance check. They'll increasingly want a partner who can help them make the best technical and financial decisions for an asset throughout its entire lifecycle and utilize it in the most efficient way. That might mean repairing an engine, sourcing used serviceable material, extending an aircraft's operating life or deciding when part-out makes more economic sense than another maintenance investment.
I also expect data to play a much bigger role in these decisions. Better visibility into asset condition, maintenance history and parts availability will allow companies to make more informed choices.
The aftermarket of the future won't just be about fixing aircraft. It will be about helping customers get the maximum value from every aircraft, engine and component, for as long as it makes economic and operational sense. I believe the relationship between MRO providers and airlines or asset owners will also change. Instead of a traditional customer-service relationship, we will see a much stronger partnership approach, where both sides work together to maximize the value and performance of aviation assets.
Laura Roke will speak at a conference session about circular and sustainable MRO at MRO Europe on Wednesday, Oct. 28.
Related Content