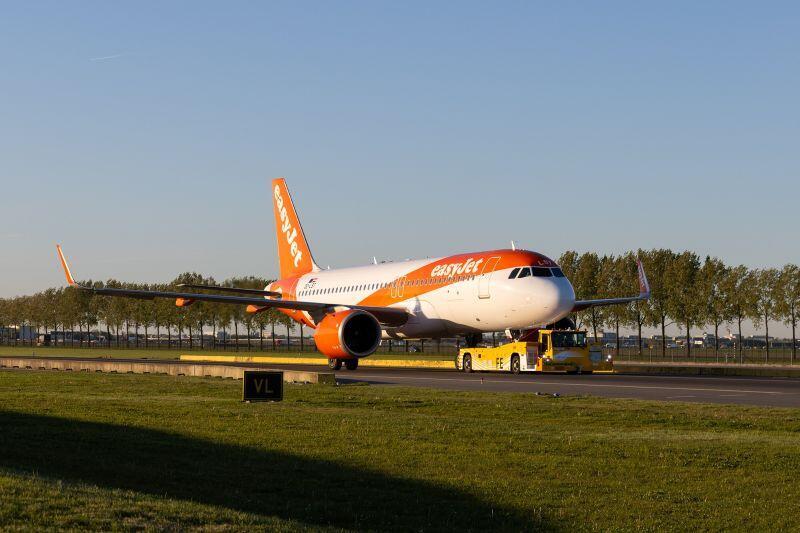
EasyJet A320neo at Amsterdam Airport Schiphol.
As the global aftermarket convenes in Amsterdam for the 2026 edition of MRO Europe, this week’s Flight Friday looks at how European operators have trended over recent years.
If we rewind back 12 months and look at aggregated flights compared to September 2024, the data shows that three of the four aircraft classes were in the positive. Widebody utilization led the charge, up almost 4.5% year over year.
Both narrowbody and regional jet utilization were also up in 2025, 3%+ and 2%+ respectively. Regional turboprop utilization, however, slipped back a fraction compared to 2024.
Fast forward to September 2026, and narrowbody utilization continues to grow, up another 3%+. Even with the turmoil of events in 2026 and the doubling of the cost of jet fuel, the narrowbody market shows its ability to adapt to these changing conditions, with good per-seat costs even on a single-aisle aircraft.
Regional turboprops actually recover some utilization in 2026, with a small uptick from 2025.
However, the global uncertainty has led to a drop in widebody utilization, as European operators scale back their operations to the Middle East, which traditionally relied on the twin-aisle aircraft to do those rotations.
The other “loser” is the regional jet market. A large part of this is a result of Lufthansa’s decision to close its CityLine subsidiary, which was a “victim,” in part, of the increased fuel prices after the Middle East conflict started, and operators’ decision to upgauge some of their fleets/routes to the narrowbody aircraft.
Related Content