This article is published in Air Transport World part of Aviation Week Intelligence Network (AWIN), and is complimentary through Oct 24, 2026. For information on becoming an AWIN Member to access more content like this, click here.
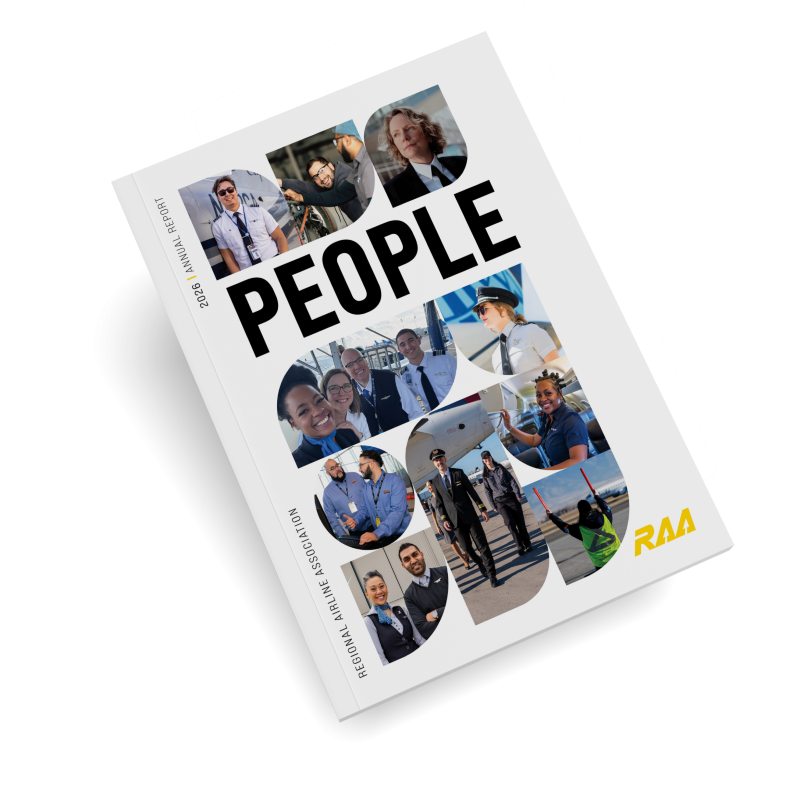
Cover of RAA annual report.
WASHINGTON—US regional airlines drove all growth in scheduled passenger departures during 2025 as operators rebuilt their workforces and returned aircraft to service. However, activity remains well below pre-2020 levels.
The Regional Airline Association’s (RAA) 2026 annual report shows regional carriers operated an average of 8,661 departures per day last year, up 8.3% from 7,998 in 2024. Departures by all other US airlines declined 0.5% to 16,675 per day.
Overall US departures increased 2.4%, meaning the domestic industry would have recorded a slight contraction without the regional sector’s recovery.
Regional airlines completed 3.16 million departures during 2025, compared with 2.92 million a year earlier, and carried 142.9 million passengers, an increase of 6.8%. Regional carriers operated 34.2% of all scheduled US passenger departures, comprising a 28.8% share for RAA members and 5.4% for other regional operators.
The figures mark a second consecutive year of departure growth following a low point in 2023, when regional carriers operated 7,292 flights per day. RAA attributed the rebound partly to lower pilot attrition, which enabled airlines to rebuild crews and reactivate parked aircraft.
At the height of the pilot shortage in 2022, regional airlines grounded about one-quarter of their fleets, contributing to reduced frequencies and the loss of service at hundreds of smaller communities. Aircraft delivery delays at larger carriers subsequently slowed their recruitment, easing some of the pressure on regional airline staffing.
However, the latest capacity increase has outpaced passenger growth. Available seat miles rose 10.4% to 83.67 billion in 2025, while revenue passenger miles increased 8.4% to 66.93 billion. Average load factor declined from 79.5% to 78.2%.
Average seating capacity in 2025 remained unchanged at 68 seats per aircraft, compared with 64 in 2019, reflecting the longer-term move toward larger regional jets. Average passenger trip length also increased by 1.5% year on year to 469 mi.
Despite the recent improvement, the regional network remains materially smaller than before 2020. Departures were 17.1% below the 3.81 million operated in 2019, while passenger numbers remained 13.5% lower than the 165.2 million carried that year.
Available seat miles were about 18.2% below 2019 levels, and average daily departures remained almost 1,800 lower. The figures indicate that larger aircraft and longer average stage lengths have enabled passenger traffic to recover faster than frequency.
The recovery is also being delivered by fewer operators. The number of US-certificated regional carriers has fallen from 66 in 2019 to 56 in 2025.
Regional airlines served 637 US airports during 2025, equivalent to 93.7% of airports receiving scheduled passenger service. At 434 airports, regional carriers provided the only scheduled passenger flights.
Regional airlines accounted for 89.2% of scheduled service in West Virginia, 85.4% in Alaska and 83.5% in North Dakota. Their shares exceeded 70% in Arkansas, Vermont, Kansas, South Dakota, Alabama and Mississippi, as well as the US Virgin Islands.
The RAA report estimates that scheduled passenger service at small-community airports supported 1.2 million jobs, $57 billion in payroll and wages and $190 billion in economic activity during 2025. The analysis was commissioned by RAA and conducted by The Meehan Aviation Group.
Related Content