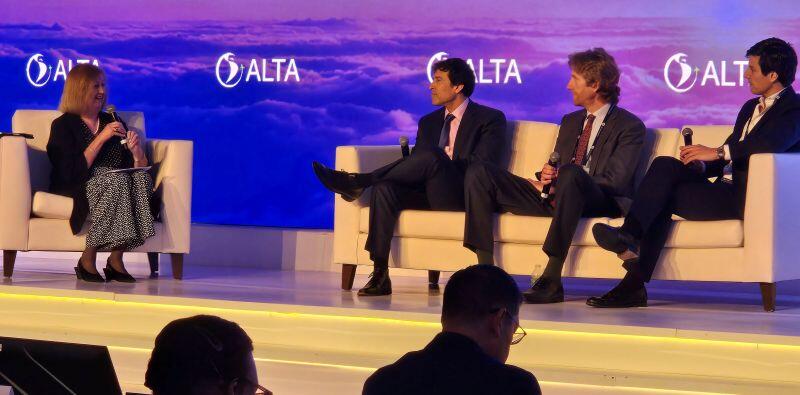
Financial analysts (L to R) Michael Linenberg, James Simpson and Carlos Garcia Martin speaking at the ALTA AGM on a panel moderated by ATW Editor-in-Chief Karen Walker.
MEXICO CITY—Latin American airlines with scale and the ability to attract premium passengers are best positioned to weather continued high jet fuel prices, according to financial analysts and airline CFOs.
The airline industry has had to make significant adjustments since the start of the Iran war in February sent fuel prices soaring, Deutsche Bank analyst Michael Linenberg told the Latin American and Caribbean Air Transport Association (ALTA) AGM and Airline Leaders Forum in Mexico City. But passenger demand remains resilient in the region with the largest carriers able to offset a sizable portion of the fuel cost increase with higher revenue generation, he said.
Latin American airlines’ fuel expense is expected to be $3.4 billion higher for 2026 than was forecast in February, according to Linenberg. But higher fares and a focus on premium products are expected to enable the industry to generate $2.8 billion more operating revenue for the year than was forecast in February, he said.
The expected 2026 earnings before interest and taxes (EBIT) margin for Latin American airlines “has gone from about 10.9% [predicted in February] to now down to somewhere in the mid 8% range,” Linenberg said. “That is still a very respectable EBIT margin, and you can see how hard the industry is pushing on raising fares and finding revenue to offset the higher fuel prices. The industry will recapture 81% of the higher fuel prices this year through higher revenue.”
He added that large Latin American airline groups, such as LATAM Airlines and Abra, are able to withstand headwinds through scale, product diversification and leaning into premium offerings.
Abra CFO Manuel Irarrazaval, also speaking at the conference, said bringing together Colombia’s Avianca and Brazil’s Gol under one parent company has enabled the group to withstand the surge in fuel costs. “Our thesis was that you needed to have scale across the whole region,” he explained. “We brought Avianca and Gol together, and we are now operating them as one airline— different brands, but one airline. This gives us the scale to be able to face this. Fuel went up, and that of course impacts us as it impacts everybody, but the scale will allow us to absorb these shocks better.”
Even as fares have pushed upward, demand in the region remains strong, with revenue passenger kilometers (RPKs) growing faster than any region in the world in August, according to IATA.
“One thing that Latin America clearly has going for it is the demand is there,” S&P Global’s Head of Aviation Research James Simpson said. “One of the biggest problems that we see in Latin America is airport congestion. That’s a double-edged sword. Of course, that limits how fast you can see demand grow, but it shows that what is available is being maximized because the appetite is there for air travel.”
Larger airlines with strong balance sheets are best able to maximize that capacity, Boston Consulting Group analyst Carlos Garcia Martin said.
“We have the demand here,” he explained. “Clearly, there is an opportunity to have some consolidation [such as the pending merger between Mexican airlines Viva Aerobus and Volaris]. With all the challenges that we are seeing right now from fuel prices [and government policies not favorable to airlines], the earnings are still profitable. Latin American airlines are still really fighting, and I think this is what we’re going to continue to see.”
Linenberg said smaller airlines, particularly ULCCs, are in a weak position in the current environment, pointing to the demise earlier this year of Spirit Airlines in the U.S. and Flybondi in Argentina.
“High fuel prices will hurt the whole industry, but it could prove to be fatal to some of the weakest carriers—like Spirit and Flybondi—and as those airlines exit the aviation ecosystem, it creates more opportunities for the bigger, stronger carriers,” he explained. “It’s going to be those smaller carriers that are going to really struggle.”
The big Latin American airlines are focusing more on generating premium revenue, taking advantage of the fact that economic uncertainty affects higher-end passengers less than price-sensitive flyers, Linenberg said. “The airlines that lean into premium are going to do quite well,” he added.
Aeromexico CFO Ricardo Sanchez, also speaking at the ALTA conference, said the carrier has put a “particular emphasis” on premium passengers as a strategy to withstand higher fuel costs. “What we have tried to do is really recapture as much of the [fuel price rise] as possible by transferring part of this extra cost to our passengers, and the focus of our business model has been ... on the premium passengers and the premium product,” he said. “We reported in the second quarter that the recapture [of higher fuel costs] was around 76% ... What has been amazing is that demand continues to be resilient and continues to hold up.”
Linenberg noted that Latin American airlines consume around 5 billion gallons of jet fuel annually. “So, every dollar increase is a $5 billion headwind that Latin American carriers have to find a way to overcome,” he said. “You’re looking at about a 10% increase in revenue needed to offset a $1 sustained increase in jet fuel prices on an annual basis. Right now, if you look at where we were at the beginning of the year and where we are today, we’re looking at a jet fuel price on average that’s up about $1.50 to $2. So, we’re talking about a 20% increase in top line industry sales needed to get back to where we were at the start of the year.”
Related Content