Why Aerospace and Defense Suppliers Can’t Scale on Demand Signals Alone
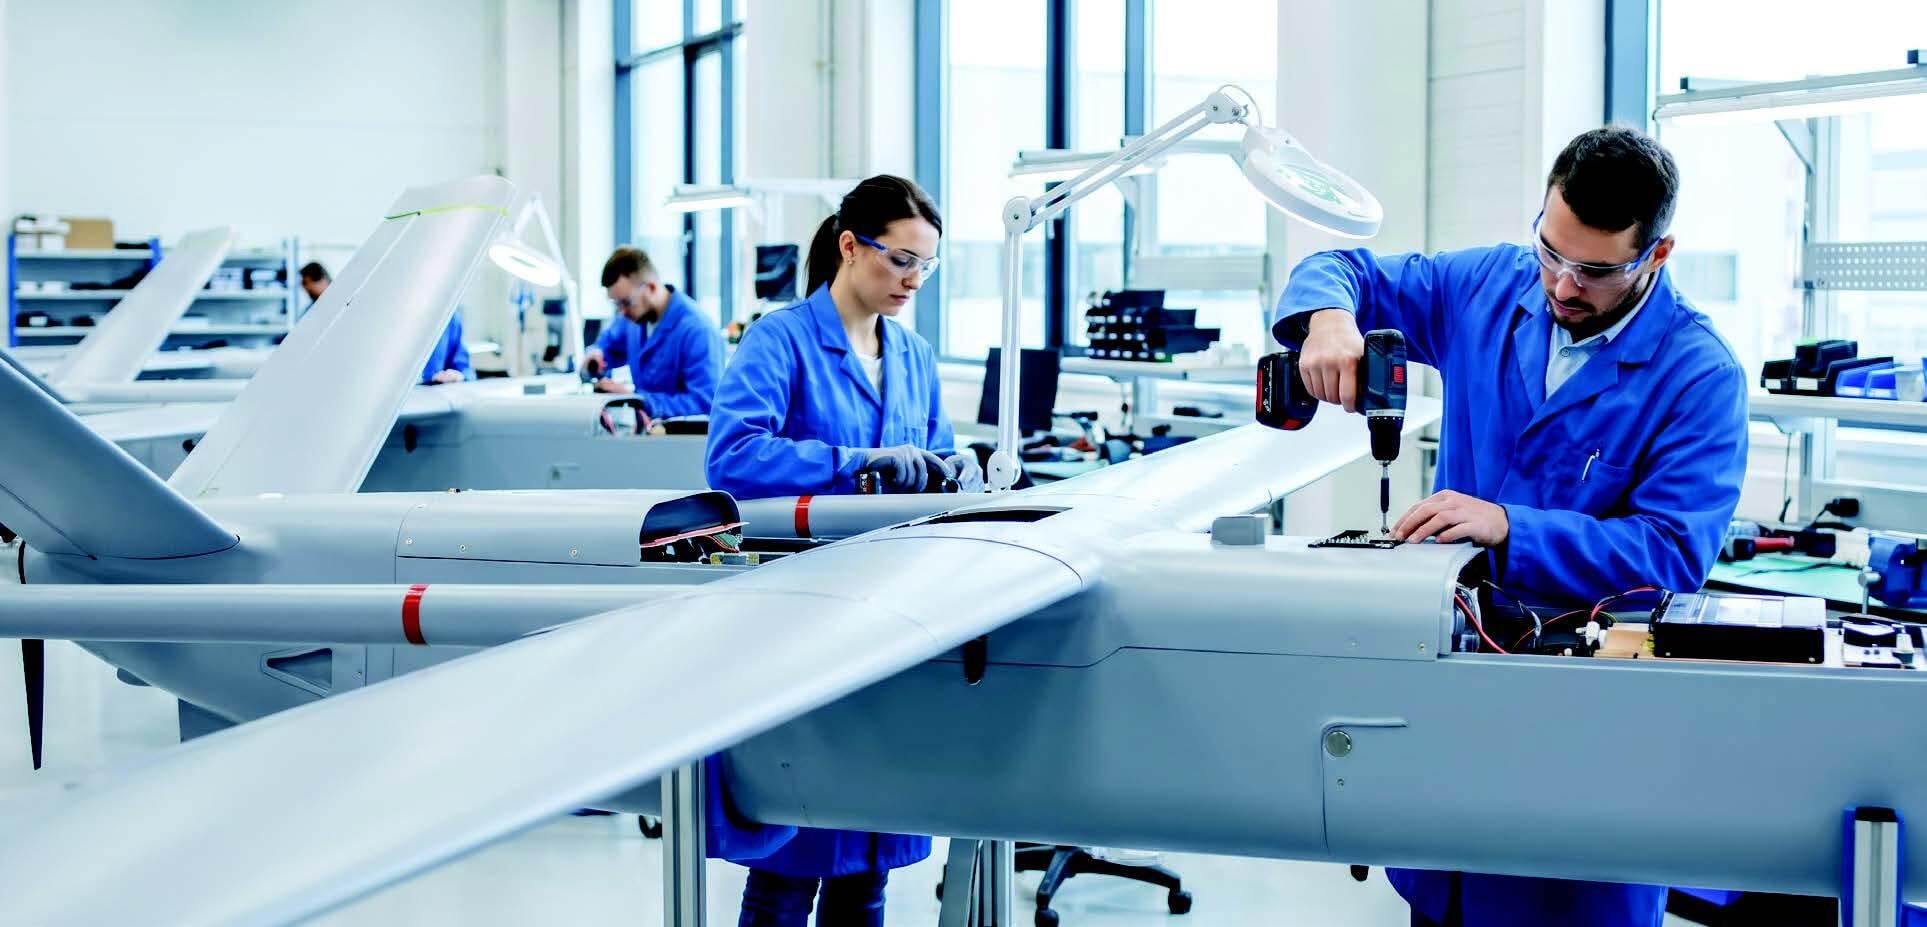
Aerospace and defense manufacturers are being asked to ramp production to surge volumes — often multiples of current output — as commercial, defense and space demand collide on the same strained supply base. Aviation Week spoke with Ashley Ransom and Aaron Cooke, Directors in PwC’s Aerospace & Defense practice, about why ramp readiness is now a board-level issue and what separates companies that scale from those that struggle.
Aviation Week: Where are the biggest bottlenecks today as companies prepare for higher production rates — inside companies, in the supply base, or further upstream in materials and specialized components?
& Defense, PwC
Ashley Ransom: More and more, the pressure is showing up in the supply base, and it’s not evenly distributed. It’s a weakest-link problem, where
the overall rate is set by whichever node is most constrained. Many raw material suppliers report zero ability to scale beyond double their output. Visibility also drops off outside a company’s own walls, so a Tier 1 may not know there’s a problem until a delivery gets missed. It’s not just complex assemblies, either. One shortage of a specialty fastener can force a program to change its rate projections.
Director, Aerospace
& Defense, PwC
Aaron Cooke: The industry is built to stretch existing capacity incrementally — 10 to 50% — not surge to multiples of current output. That traces back to decades of staying asset-light and outsourcing globally, a strategy COVID, deglobalization and active conflicts have upended. The value chain runs many layers deep — each company with its own history, incentives and risk appetite — driving coordination complexity and blunting demand responsiveness. Common levers like dual-sourcing fall short because the supplier pool is fixed, capital needs are high, demand is uncommitted and alternatives require third-party qualification. Skilled trades are a major constraint, too; those skills take years to develop and have been deprioritized across the developed West for decades. Add in long equipment lead times and inflationary input costs, and companies are left wondering whether they can ramp at cost structures that work.
AW: How important is demand certainty in getting suppliers to invest ahead of the ramp? Where does the funding come from and where should that investment be focused?
AR: It comes down to trust. Suppliers know demand is rising, but they need to trust that signal enough to put capital behind it, and that trust erodes further down the chain. Primes tend to see demand come in higher than forecast; raw-material suppliers often see the opposite. A hedge at every tier creates a cumulative bullwhip effect, where the little guys are left holding the bag. A bigger forecast isn’t necessarily more credible; suppliers need an actionable commitment with firm orders they can take to the bank. Multi-year framework deals help, but the funding isn’t real until Congress passes the budget.
AC: Investing with confidence starts with longterm, committed demand. Next is the ability to finance it through debt, cash reserves, government backed or private capital. Beyond that, it will take a recalibrated risk appetite: not “betting the farm” on one risky business case, but building a portfolio of transformational bets alongside tactical moves like adding shifts and improving yields. Most sub-tier suppliers still finance capacity through bank loans against orders. These orders take time to flow down, so there’s opportunity to gain share by investing ahead of committed demand via partnerships, federal vehicles or private and venture capital.
AW: What actions and investments should companies be making now to de-risk the ramp?
AC: Start with what you control: identify local constraints that will materially impact ramp readiness over the next 12 months, even if some require funding you don’t have yet. There’s often 10 to 50% latent capacity in the system that can be unlocked by improving yields, scheduling and productivity. Longer term, net-new capacity must be built on bottleneck processes. Investments in new factories, tooling or vertical integration to establish resilience and control strategic capabilities will pay off if executed smartly. There’s a flywheel effect, too: as customers and suppliers feel the ramp accelerating, orders gravitate toward you as a reliable source — buying time for longer-term bets to pay off.
AR: Primes and larger suppliers have to get more creative deeper in the chain to close funding gaps and capacity constraints — through targeted capital investment, U.S. government co-investments, on-site recovery teams and designing out constrained parts. Federal funding can help, but smaller suppliers often lack the resources to access it alone. Automation and physical AI are showing real promise for easing dependence on hard-to-find trade skills, but must be paired
with the digital capabilities and execution maturity to support operations.
AW: What will separate companies that successfully ramp from those that struggle over the coming years?
AC: Products and production systems need to be designed to scale from the outset. Easier said than done since A&D produces some of the most regulated, technologically advanced products in the world. Innovation, scalability and resilience must now be equal-weighted and engineered into all aspects of the portfolio and enterprise. As production becomes increasingly digitized, companies that control strategic manufacturing processes, and the data they generate, will be better positioned to ramp volumes, iterate fast and capture value.
AR: The winners will go beyond their own four walls. Engineering, operations, supply chain and suppliers need to work off one integrated ramp plan, with real alignment on what scales, when and where — not five entities independently guessing at the same demand curve while holding their cards close. Too often, planning and operations work off two different versions of reality, so a schedule that looks great on paper falls apart on the floor. The operating model of the future must be more coordinated, responsive and digitally connected. Most companies aren’t starting from zero; they’re probably a handful of strategic decisions away from real readiness.
About the Experts
Ashley Ransom has 15 years of experience leading large-scale digital and operational transformations, M&A carve-outs and cost-performance improvement across aerospace, defense and industrials.
Aaron Cooke has 15 years of industry and consulting experience across aerospace and defense, specializing in operations strategy, M&A value creation and enterprise performance improvement.
Related Content