A&D Due Diligence: What Buyers Ask, How Sellers Should Prepare
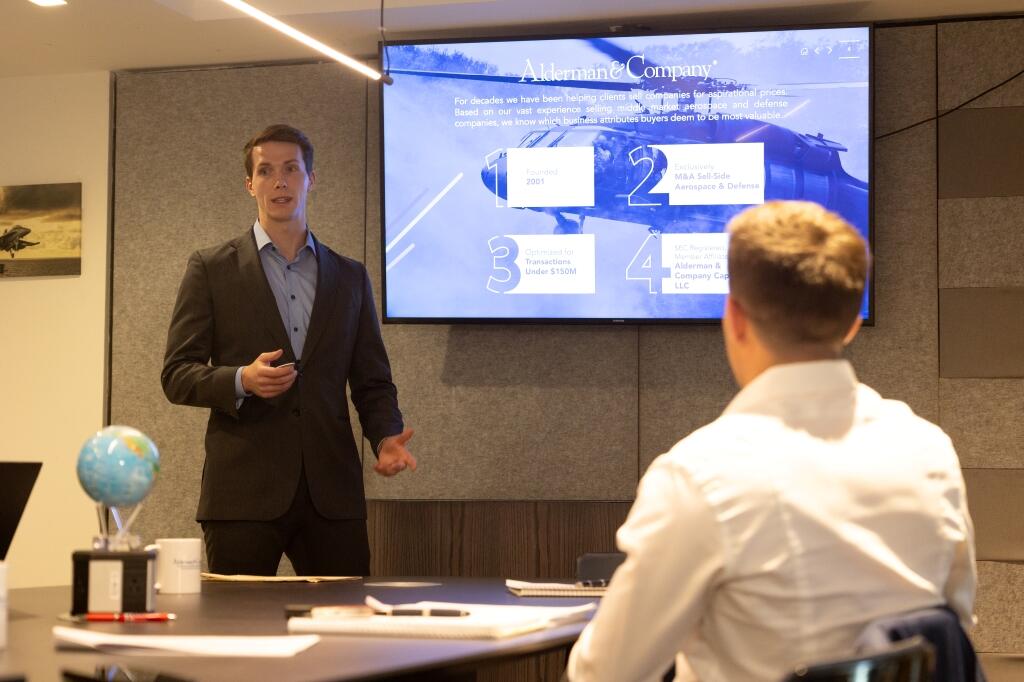
With buyer due diligence more rigorous than ever, aerospace and defense business owners who wait until they’re in the market to prepare often pay for it in price and terms. Aviation Week spoke with Ryan Kirby, a partner at Alderman & Company, about the due diligence patterns his firm has tracked across 25 years of sell-side aerospace and defense M&A — and what buyers are digging into right now.
Q: After 25 years of Alderman & Company advising on sell-side middle-market aerospace and defense M&A, what pattern in buyer due diligence has changed the most?
Ryan Kirby: Buyer due diligence follows familiar themes. Buyers want to understand a company’s earnings and growth plan, and they’ll validate everything from a legal, financial, environmental, and IT perspective before finalizing a purchase agreement. One of the noteworthy changes in due diligence is the quality-of-earnings report, which has become standard in the lower middle market of aerospace and defense over the past five years — sellers now prepare a quality-of-earnings report because nearly every deal in this size range requires one. But the core focus areas for buyers, earnings and projections, haven’t changed, and we don’t expect them to.
Q: Where do sellers most often undercut their own financial credibility with buyers?
RK: Buyers focus on what they’re about to own, so projections get scrutinized more than most sellers expect. Buyers typically ask for a five-year projection with the most detail in the nearest years. An optimal set of projections is realistic and defensible. Projections should not be too aggressive, or they will get picked apart in diligence. They should not be too conservative either, which would mean that a seller would leave value on the table. Another important area of financial credibility, especially for our A&D manufacturing clients, is inventory — particularly obsolete and excess write-off policies and procedures, because that’s where earnings can be overstated. The last important point to note for sellers is that they need to hit monthly and quarterly targets throughout the sale process, as it proves, in real time, that their business is meeting its forecast.
Q: Are buyers focused on customer concentration, pipeline and program mix?
RK: Yes. Buyers love data — the more owners have that ties back to their Compiled, Reviewed, or Audited financials, the better. For example, buyers will ask for revenue by part number, service, product, program, customer, geography, etc. Business owners should think about what they already track — whether it’s revenue metrics, operational metrics, or pipeline statistics — and see if there are any natural additional data points they could be collecting. Additionally, A&D owners should avoid having only one person in the business who is capable of running these data exports. If an owner is not tracking enough data for a buyer to validate the company’s performance, then I recommend starting now.
Q: Where does operational and supply chain diligence catch sellers off guard?
RK: Operations is rarely where our clients struggle. Individual or family-owned aerospace and defense businesses tend to be operational experts, and it is their core competency and their focus. Areas like accounting and projections usually get less of management’s attention at smaller A&D companies than their customers and operations. One area buyers focus on is supplier concentration. They’ll review cost-by-supplier detail and any areas of the supply chain considered sole-source. Sellers can get caught off guard here because they’ve been busy winning business and running the company rather than tracking supplier concentration risk. To note, we’ve seen middle-market A&D firms spending significantly more time building stronger supply chains in the past few years than previously – directly addressing this potential due diligence issue.
Q: Do compliance issues like ITAR and CMMC derail middle-market A&D deals?
RK: Regulatory compliance is seldom an issue addressed early in buyer due diligence. It is usually a buyer priority that falls behind issues like earnings, margins, backlog, and projections. However, regulatory compliance is on their list, and buyers will not acquire the target business if there are substantial problems with the seller’s compliance. Seldom do we see deals die due to compliance. More often we see substantial delays and modest price reductions caused by the seller rushing to fix a compliance problem the buyer found late in due diligence.
Q: What’s the first step for an owner who’s just starting to think about selling?
RK: We always recommend starting by understanding what they want personally. We’ll ask if they enjoy running the company, or if a son, daughter, or trusted manager might want to take over. Often that reframes whether now is the right time in their career to sell. Once an owner fully formulates their personal goals and decides selling now is best, they should assemble a team of advisors they can trust. Selling a business is one of the most complex and time-intensive things an owner will ever do during their business career. An owner should seek an M&A attorney with substantial experience selling companies like theirs, an M&A banker who specializes in their industry, and an accountant who will produce a quality-of-earnings report and then defend the numbers in buyer due diligence. As we always say, the M&A process is like any other process in business; the better an owner prepares and the more talented the sell-side team, the better the results.
About the Expert
Ryan Kirby is a partner at Alderman & Company, where he advises aerospace and defense companies on middle-market sell-side mergers & acquisitions, valuations, and sale preparation. He has led and supported engagements across the aerospace and national security sectors.
Ryan serves on the Emerging Professionals Board of Vertical Aviation International and the Young Alumni Board of the O’Maley College of Business at Embry-Riddle Aeronautical University. He has been quoted as an industry expert by Aviation Business News, Octus, Homeland Security ScaleUp (FedTech), VAI, T-Minus Space Daily, and other industry organizations and media. Ryan holds the SIE, Series 79, and Series 63 registrations. He earned a BS in Business Administration (Accounting and Finance) and an MBA (Finance), both summa cum laude, from Embry-Riddle Aeronautical University.
Related Content