Middle East sees fastest end-2009 traffic growth
According to the International Air Transport Association (IATA), Middle Eastern carriers generated the fastest growth in passenger traffic at the end of the year with a 19.1% increase in December (and 11.2% growth for the entire year). These gains result from Middle Eastern carriers taking a larger share of long-haul connecting traffic over their hubs.
However, overall full-year 2009 demand statistics for international scheduled air traffic worldwide, showed the industry ending 2009 with the largest ever post-war decline. Passenger demand for the full year was down 3.5% with an average load factor of 75.6%. Freight showed a full-year decline of 10.1% with an average load factor of 49.1%.
Giovanni Bisignani, IATA’s Director General and CEO said: “In terms of demand, 2009 goes into the history books as the worst year the industry has ever seen. We have permanently lost 2.5 years of growth in passenger markets and 3.5 years of growth in the freight business."
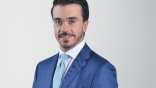
Above: Giovanni Bisignani
International passenger capacity fell 0.7% in December 2009 while freight capacity grew 0.6% above December 2008 levels. Yields have started to improve with tighter supply-demand conditions in recent months, but they remained 5-10% down on 2008 levels. Bisignani said: “Revenue improvements will be at a much slower pace than the demand growth that we are starting to see. Profitability will be even slower to recover and airlines will lose an expected US$5.6 billion in 2010.”
Seasonally adjusted demand figures for December compared to November 2009 indicate a 1.6% rise in passenger traffic while freight remained basically flat with a 0.2% decline.
International Passenger Demand
December 2009 passenger demand recorded a 4.5% improvement compared to December 2008, with a load factor of 77.6%. While this is an 8.4% demand improvement from the February 2009 low point, it is still 3.4% below the early 2008 peak.
International Freight Demand
December 2009 freight demand showed a 24.4% improvement on December 2008 with a load factor of 54.1%. This improvement is exaggerated by the exceptionally weak performance in December 2008 which was the low point on the cycle. Freight demand is still 9% lower than the peak in early 2008. Optimism is returning to the industry as purchasing managers survey indicators reached a 44-month high in December pointing towards increased freight volumes in the coming months.
Middle East carriers ended the year better than peak levels by 7%.
A challenging year ahead
Bisignani said: “The industry starts 2010 with some enormous challenges. The worst is behind us, but it is not time to celebrate. Adjusting to 2.5-3.5 years of lost growth means that airlines face another spartan year focused on matching capacity carefully to demand and controlling costs.
“We also face a renewed challenge on security as a result of the events of 25 December 2009. The approach of the Obama administration is encouraging with Department of Homeland Security Secretary Janet Napolitano visiting IATA’s offices in Geneva to engage industry to find solutions. We agreed that governments and industry must cooperate and we are preparing for a meeting in the coming weeks to follow-up on our recommendations which focused on finding more efficient ways to implement intelligence-driven and risk-based security measures."
Full December 2009 traffic results:
| Dec 09 vs. Dec 08 | RPK Growth | ASK Growth | PLF | FTK Growth | AFTK Growth |
| Africa | 3.1% | 1.1% | 71.5 | 33.0% | 4.5% |
| Asia/Pacific | 8.0% | -0.9% | 78.2 | 34.4% | 7.7% |
| Europe | -1.2% | -3.5% | 76.0 | 5.2% | -9.5% |
| Latin America | 7.1% | 1.4% | 76.0 | 37.4% | 20.0% |
| Middle East | 19.1% | 14.1% | 76.3 | 32.1% | 13.7% |
| North America | -0.4% | -5.4% | 82.2 | 23.9% | -7.8% |
| Industry | 4.5% | -0.7% | 77.6 | 24.4% | 0.6% |
| 2009 vs. 2008 | RPK Growth | ASK Growth | PLF | FTK Growth | AFTK Growth |
| Africa | -6.8% | -3.3% | 69.9 | -11.2% | -3.3% |
| Asia/Pacific | -5.6% | -6.3% | 73.9 | -9.2% | -11.0% |
| Europe | -5.0% | -4.4% | 76.4 | -16.1% | -10.7% |
| Latin America | 0.3% | 1.7% | 73.0 | -4.0% | 1.4% |
| Middle East | 11.2% | 13.6% | 73.3 | 3.9% | 6.8% |
| North America | -5.6% | -5.4% | 79.6 | -10.6% | -9.7% |
| Industry | -3.5% | -3.0% | 75.6 | -10.1% | -8.4% |
Related Content